How to use Direct Payments for home care in the UK
Bruno Ceccolini
Co-founder · Care Consultant
Key Takeaways
A Direct Payment is council money, after a care needs assessment, so you arrange home care yourself instead of taking the visits they commission.
It is still the council's money after it lands, which is why they ask for invoices. Paying for home care covers the means test that sits underneath.
The card can sit in a kitchen drawer for weeks while the mornings still have nobody in them. That is the bit families are not warned about.
The card in the fruit bowl
A daughter in Wandsworth has had the prepaid card since early August. Seven hours a week on the plan. Mum is 82, shower and breakfast. The council paid the first lump onto the card. The card is in the fruit bowl, next to the bananas that go brown because nobody is there at 8am to throw them out.
She has been reading employer PDFs at 11pm. PAYE, holiday accrual, a sample contract she does not understand. She has not hired anyone.
I keep seeing this version. The money arrived. The person did not.
What is a Direct Payment for home care?
A Direct Payment is money from your local council, after a care needs assessment, so you buy the home care in the care and support plan yourself instead of the council booking an agency. The NHS calls that taking your personal budget as a Direct Payment.
GOV.UK is blunt: you can only get one if social services have already assessed that you need care and support. You have to be 16 or over. England, Scotland, and Wales all run a version. Northern Ireland has its own route.
It is not Attendance Allowance and it is not Carer's Allowance. Those are DWP benefits. A Direct Payment stays council money, which is why unused pounds get clawed back.
On 31 March 2026, the Department of Health and Social Care counted 490,000 people in England on long-term support in the community. That figure includes council-arranged home care and Direct Payments people use to buy their own support. The number has been climbing since April 2025.
How to apply for Direct Payments for home care
Ask the council where they live for a free needs assessment. Savings do not block the assessment. In England, capital over £23,250 usually means they pay the social-care cost if the council later agrees there is a need. The home they live in is normally left out of that test for care at home.
If they are eligible, you should get a written care and support plan and a personal budget. Then you ask for some or all of that budget as a Direct Payment. Age UK's factsheet on personal budgets (current to November 2026) says the council has a duty to offer this if the legal conditions are met. They should not pressure you into it either.
Money usually arrives on a prepaid card or into a separate bank account. If the financial assessment says your parent must contribute, that contribution often has to go into the same pot first. The council then tops it up.
ADASS's Spring Survey 2026 found more than 400,000 people in England waiting for an assessment, for care or a Direct Payment to start, or for a review. A card in August can still mean you asked in April.
What you can spend Direct Payments on
Statutory guidance says a Direct Payment is meant to be used flexibly, with no unreasonable restriction, as long as it meets eligible needs in the plan. Age UK quotes that line because some councils still try to shrink it to a 30-minute rota.
You can usually pay a personal assistant you recruit, a home care agency, or some equipment if it is in the plan. Short breaks are possible, with limits.
You cannot usually pay for permanent residential care, ordinary bills, food, or NHS treatment. The Care and Support (Direct Payments) Regulations 2014 also say you cannot pay a spouse, civil partner, or a close relative living in the same household, unless the council decides that is necessary. A daughter in the next borough is a different question. Ask, in writing.
You can take a mixed package: council-arranged showers, Direct Payment for the Tuesday outing. You can nominate someone to manage the money. If they lack capacity, that person is an "authorised person", with extra checks.
Keep the invoices. Councils review Direct Payments at least once in the first six months, then at least yearly. Some claw back anything sitting unused above a few weeks of contingency. The fruit-bowl card is not a rainy-day fund.
The employer question Google throws up first
If you employ a personal assistant, you are an employer. Skills for Care's toolkit is the honest version of that job: recruitment, a written contract, PAYE, National Insurance, holiday pay, a workplace pension if it applies, employer's liability insurance, and cover when they are off. From April 2026 the National Living Wage for people aged 21 and over is £12.71 an hour. The Direct Payment should include those on-costs. If it does not, the budget is too small. Ask them to show the calculation.
This is where the Wandsworth daughter has been stuck. She thought the card meant she had to become Mum's employer by Friday.
You can spend it without a PAYE scheme
You can use a Direct Payment to pay a home care agency, or a self-employed carer, so you are buying a service rather than employing staff. Age UK is explicit about that split. The council still wants invoices that match the plan. You still need to be satisfied about DBS, right to work, and who actually turns up.
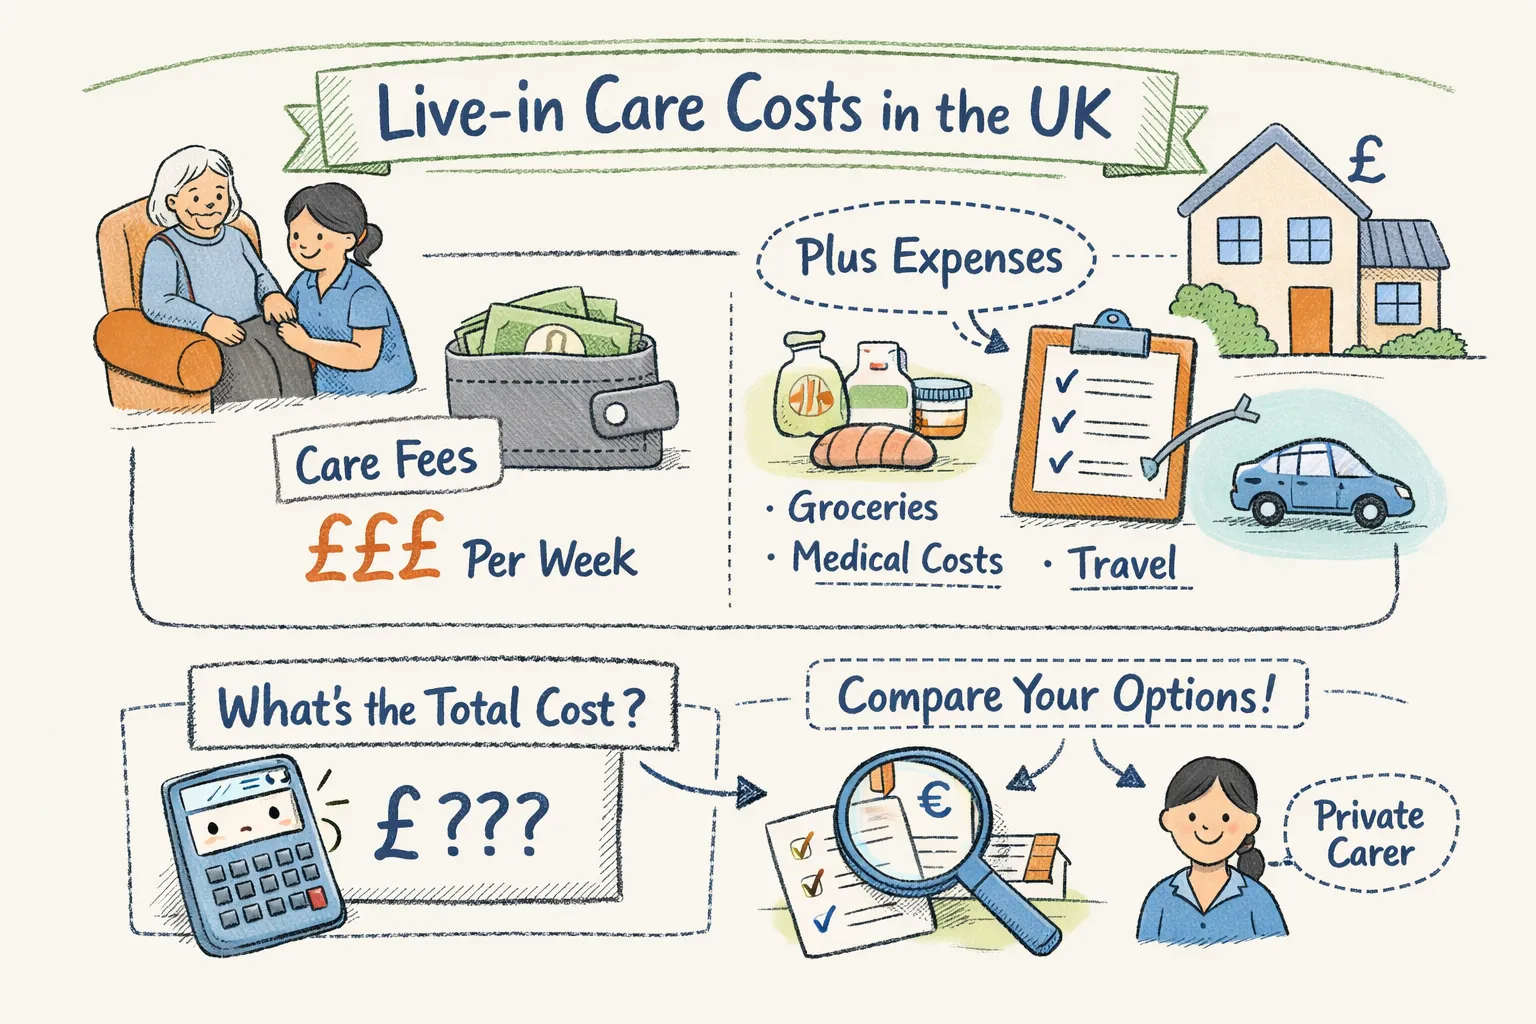
The NHS says help at home from a paid carer often costs £15 to £30 an hour, depending on the area and what is needed. London and tight morning slots sit higher. Hourly rates in 2026 is the fuller spread. If the personal budget was built on the council's contracted rate, and the person you want charges more, you may have to top up privately. Get that in the plan if you can.
A son in Chapel Allerton had eight hours a week on the Direct Payment after Dad's second fall. He did not register as an employer. He paid a named visiting carer, 7.30 to 9.30, Monday to Friday, on invoices the council accepted. Dad still does Sundays. Falls are a GP conversation.
If the needs are primarily health, that is a personal health budget under NHS Continuing Healthcare, which is a different pot. Claim Attendance Allowance anyway. It will not cover seven mornings on its own.
What I cannot tell you yet
In September 2026 the Homecare Association published a paper arguing councils should stop buying care in isolated minutes and move toward a portable personal funding entitlement the person directs. I do not know whether that arrives in time to help anyone with a card in a fruit bowl this autumn. The National Care Service talk has the same problem: a direction of travel, and no date on the prepaid card.
How Match with Care can help
A Direct Payment is only useful if a real person is in the kitchen at 7.30. The card does not do that on its own.
Match with Care is a managed introductory care marketplace. We interview carers, check enhanced DBS, right to work, and references, then show you profiles so your parent can meet someone before they have a key. We are not a traditional domiciliary care agency, and we are not CQC-registered as a care provider. Introductory matching does not work that way.
What we can do is help you use the hours on the plan, often around 20 to 30 per cent below typical agency quotes, with a care advisor if the match is wrong. Families paying from a Direct Payment usually send our invoices to the council the same way they would send an agency's. You do not have to run PAYE to get a named person for the shower.
If you want to talk it through first, without your parent on the line, call +44 7962 657635 or email hello@matchwithcare.com.
Frequently asked
questions
A Direct Payment is money from the council, after a care needs assessment, so you arrange home care yourself instead of accepting the visits they commission. It comes from the personal budget. You spend it on the needs in the care and support plan. It is not a DWP benefit and it is not treated as taxable income.
Ask the council where the person lives for a free care needs assessment. Savings do not block that assessment. If they are eligible, you should get a care and support plan and a personal budget. Then ask for some or all of that budget as a Direct Payment. England, Scotland and Wales all run a version; Northern Ireland has its own route. You must be 16 or over.
You can usually pay a personal assistant, a home care agency, or a self-employed carer, and sometimes equipment or a short break, if it meets eligible needs in the plan. You cannot usually pay for permanent residential care, rent, food, utility bills, or NHS treatment. You also cannot normally pay a spouse, civil partner, or close relative living in the same household unless the council agrees it is necessary.
No. If you employ a personal assistant you take on PAYE, National Insurance, holiday pay, and employer's liability insurance. You can instead pay a home care agency or a self-employed carer, so you are buying a service. The council still wants invoices that match the care and support plan.
Not always. In England, capital over £23,250 usually means you pay the social-care cost if the council agrees there is a need. Below that, a financial assessment may still set a weekly contribution, which often has to go into the same prepaid card or bank account as the council's top-up. The home they live in is normally left out of that test for care at home.
Sources
5 sourcesNHS
View source“Personal budgets and direct payments”
2024
GOV.UK
View source“Apply for direct payments”
2026
Age UK
View source“Personal budgets and direct payments in social care (Factsheet 24)”
2025
Department of Health and Social Care
View source“Adult social care client level data, England: quarterly update to March 2026”
2026
legislation.gov.uk
View source“The Care and Support (Direct Payments) Regulations 2014”
2014